Useful Leadership Trait 5: Focus
B&G Leadership Series – Part 8
“Thank God for J.P. Morgan and Jamie Dimon”
The words of Bill Ackman, founder & CEO of Pershing Square Capital, during the financial markets crisis of 2008.
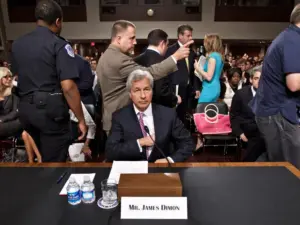
Jamie Dimon, June 13, 2012 J. Scott Applewhite / AP
Below are Dimon’s introductory statements in his testimony to the Financial Crisis Inquiry Commission on 13 January 2010:
“Throughout the financial crisis, JPMorgan Chase never posted a quarterly loss, served as a safe haven for depositors, worked closely with the federal government, and remained an active lender to consumers, small and large businesses, government entities and not-for-profit organizations. As a result of our steadfast focus on risk management and prudent lending, and our disciplined approach to capital and liquidity management, we were able to avoid the worst outcomes experienced by others in the industry.”
The “worst outcomes” that Dimon referenced included the collapses of Washington Mutual (the biggest bank failure in US history) Bear Stearns and Lehman Brothers. JP Morgan’s acquisition and absorbtion of the first two – Bear at the behest of the US government – helped limit the damage wreaked by the crisis.
In very simplified terms, the 2008 financial crisis was a direct result of the excesses in the credit derivatives market, a market created in 1993 when JP Morgan’s Peter Hancock invented the asset class. The notional size of the credit derivative market grew from $40 billion in 1996 to $17 trillion at the end of 2005 when Dimon took over as CEO of JP Morgan.
Among the reasons for the explosive growth of the asset class was the high profit margins earned by the banks that provided these products to their clients. Institutional investors bought credit derivatives because they (theoretically) provided insurance against bond and loan defaults. This in turn fueled the explosion in demand for increasingly complex debt products, aka structured credit, in a low interest rate environment.
In the early to mid 2000s, every major investment bank was active in structured credit with some of the biggest and some of the most sophisticated players battling aggressively for market dominance. As an executive recruiter paid to move structured credit traders and salespeople from one bank to another, I lived and breathed this world. Like many, I thought JP Morgan was being overly cautious in its approach to the asset class, leaving potentially huge profits on the table.
Jamie Dimon knew better than the rest of us. When asked publicly about this, he stated that the risks around structured credit were not fully understood and that JP Morgan would remain cautious until they were. Dimon even said he was comfortable letting other banks take the lead, a very rare public stance for a CEO in the ultra-competitive world of high finance.
Despite the obscene profits being made by his rivals on the Street, Dimon never lost sight of his fiduciary duty to the bank’s deposit holders, corporate clients, shareholders and employees. He never lost focus.
As Meredith Whitney aka The Oracle of Wall Street, said back in 2008, Dimon is
“a very responsible steward of shareholder capital. That’s the best thing you can say about a CEO.”
Seven years prior to the subprime financial crisis, the bursting of the dotcom bubble unleashed carnage in the technology and telecommunications sectors. With venture capital firms falling over themselves to fund internet startups, providers of telecommunications services – the “carriers” through whose network infrastrucure internet traffic flows – embarked on an arms race to build the biggest, fastest and most technically sophisticated networks. Some of the biggest network equipment manufacturers jumped in with both feet, going as far as lending money to their carrier customers to finance purchases of their own kit!
When it dawned on investors that a large proportion of the startups were built on flimsy business models, they withdrew funding en masse. Hundreds of startups failed after running out of cash. With so many of their customers out of business the carriers found themselves sitting on expensively funded networks without enough traffic to pay for them. Several went under as did some of the manufacturers who had entered into questionable financing arrangements with them.
The leadership of Bear Stearns and Lehman Brothers in the mid-noughties – much like their counterparts at Global Crossing, Nortel Networks & Lucent Technologies at the turn of the century – failed to properly assess the inherent risks and to exercise the caution expected from “responsible steward(s) of shareholder capital.” Distracted by league table rankings and the promises of bumper profits for pioneers of shiny new technologies, they were guilty of losing focus on the fundamentals of their respective businesses.
There’s that word focus again.
Focus is perhaps my one non-negotiable trait for a good leader. Leaders are faced with so many challenges, decisions and competing interests that losing focus can see them blown irreversibly off course.
I leave you with two (and a bit) questions to ponder:
- Looking back on the frenzied investments and arm races of the dotcom and subprime booms, do you see any parralels with today’s AI boom? If yes, what do you think should be the primary focus of the leaders of the software, chip-manufacturing and data centre businesses?
- Jamie Dimon’s number one focus is on Risk. As a leader in your space, what is your number one focus?
More articles on leadership here